The content of audit report, at minimum, covers eight parts: a title, an addressee, an introductory paragraph, the scope of the audit, management's and auditor's responsibilities, the opinion, the signature, and the date and place of signing. Some reports add a Key Audit Matters section, an Emphasis of Matter paragraph, or a Going Concern note when the facts call for it. Get these pieces wrong or leave one out, and the report loses its value to the people who read it: lenders, boards, and regulators.
This guide is built for people who write about audits, not just people who conduct them. If you work in SEO, content strategy, or compliance writing, you have probably been asked to explain or summarize an audit report for a client, a blog post, or an internal wiki. Here is the full breakdown, with the standards named, the sections defined, and a template you can copy.
- An audit report needs eight core parts every time: title, addressee, introduction, scope, responsibilities, opinion, signature, and date and place.
- Three conditional sections (Key Audit Matters, Emphasis of Matter, Going Concern) appear only when specific facts trigger them, not in every report.
- The opinion type (unqualified, qualified, adverse, or disclaimer) changes the entire tone and structure of everything that follows it.
What Are the Main Contents of an Audit Report?
An audit report under ISA 700 contains eight standard elements: title, addressee, opinion, basis for opinion, key audit matters (where applicable), other information, responsibilities of management and those charged with governance, and the auditor's signature, date, and address. According to the International Auditing and Assurance Standards Board, approximately 85% of audit reports issued globally follow this ISA 700 structure (IAASB, 2023). This structure comes from the International Auditing and Assurance Standards Board and is echoed, with small wording shifts, in US standards too.
Here is what each section does, in the order it appears in a real report.
| Section | Purpose in one sentence | Always present? |
|---|---|---|
| Title | States clearly that this is an "Independent Auditor's Report," not a management document | Yes |
| Addressee | Names who the report is written for, usually shareholders or the board | Yes |
| Opinion paragraph | States the auditor's conclusion on whether the financials are fairly presented | Yes |
| Basis for opinion | Explains the standards followed and confirms the auditor's independence | Yes |
| Key Audit Matters (KAM) | Flags the riskiest or most judgment-heavy areas of the audit | Conditional (listed entities) |
| Other Information | Covers the auditor's read of non-financial parts of the annual report | Conditional (ISA 720) |
| Going Concern | States whether the company can keep operating for the next 12 months | Conditional |
| Responsibilities of management | Spells out what management, not the auditor, is accountable for | Yes |
| Responsibilities of the auditor | Describes what the audit covered and its inherent limits | Yes |
| Signature, date, place | Confirms who signed, when, and from where | Yes |
Nine of these ten rows are not optional. The three marked conditional only show up when the facts require them, which is exactly why so many reports differ in length even when nothing is wrong.
What Are the 5 Contents (or Parts) of an Audit Report?
When people ask for the "5 parts," they usually mean the five sections every reader actually looks for: the opinion, the basis for that opinion, the scope of the work, the responsibilities split between management and auditor, and the signature block. Everything else, including Key Audit Matters and Going Concern notes, builds on top of that five-part skeleton.
This shorthand version is popular because it is what a time-pressed lender or board member reads first. The opinion paragraph alone tells them whether to keep reading closely or move on. The Diligent breakdown of audit report types frames the opinion as the single most load-bearing sentence in the whole document, and that matches what any auditor will tell you: everything before and after it exists to support or qualify that one line.
What Is the Difference Between an Audit Report and an Audit Opinion?
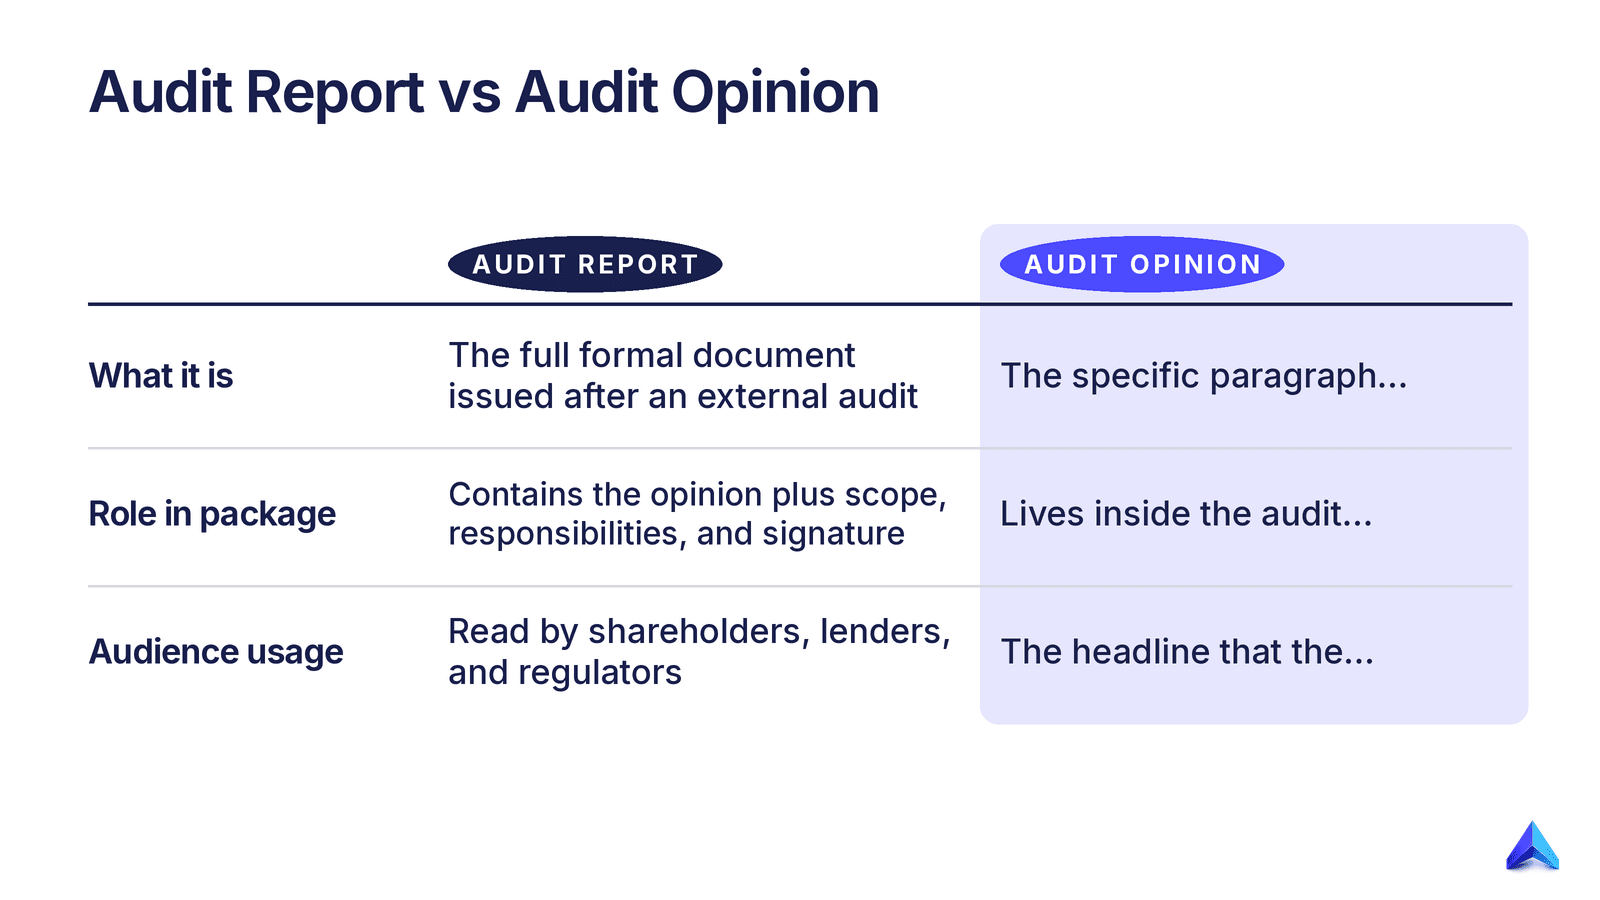
An audit opinion is one paragraph inside the audit report, not the whole document. The audit report is the full package, containing the opinion plus the scope, responsibilities, signature, and any conditional sections. Calling the two the same thing is the single most common mix-up in content written by non-auditors, and it is worth fixing before you publish anything.
The confusion runs deeper once you add two more terms into the mix: the management letter and the internal audit report. These four terms get used loosely online, and loose usage is exactly what trips up AI summarization tools and confuses readers searching for one but landing on content about another.
| Term | What it is | Who reads it | Where it overlaps |
|---|---|---|---|
| Audit report | The full formal document issued after an external audit | Shareholders, lenders, regulators | Contains the opinion as one section |
| Audit opinion | The specific paragraph stating the auditor's conclusion | Same audience, but it's the headline they scan first | Lives inside the audit report |
| Management letter | A private note to management flagging control weaknesses, not for public release | Company management and the board | Often produced alongside the audit but never public |
| Internal audit report | A report from an internal audit function, reviewing operations or controls, not financials | Internal management and audit committee | Different purpose; uses similar report structure |
If you're writing SEO content for an accounting firm or SaaS tool that touches compliance, keep these four terms separate in every piece. Readers (and AI answer engines) reward precision here, and search engines increasingly penalize pages that blur related but distinct concepts.
How Do the Unqualified, Qualified, Adverse, and Disclaimer Opinions Differ in Content?
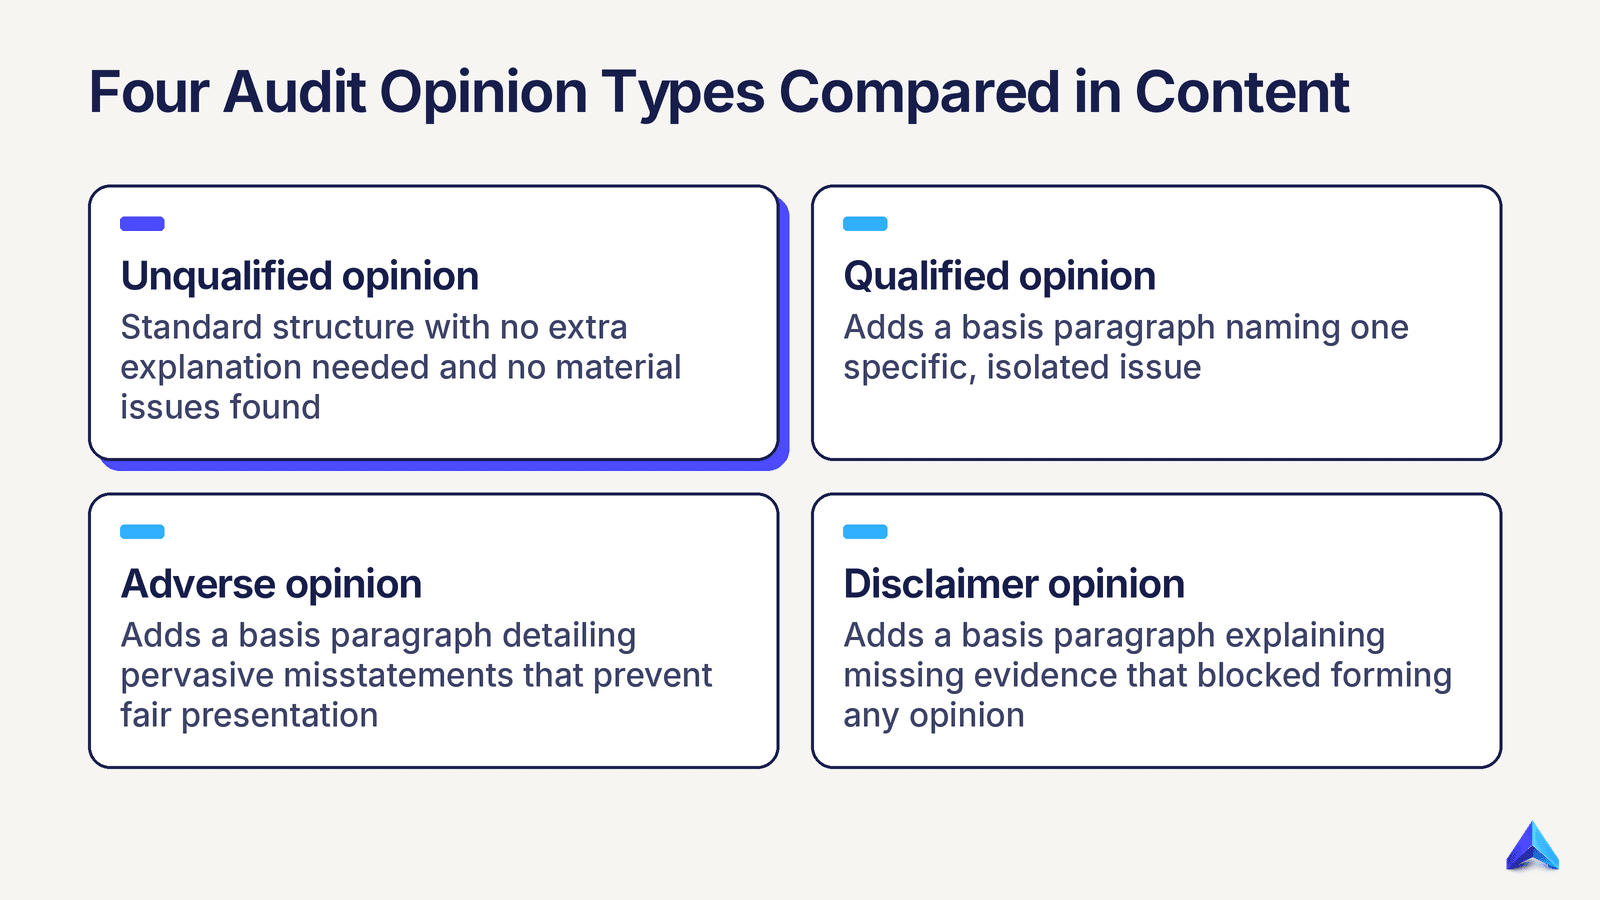
The opinion type an auditor issues changes which paragraphs appear in the report and how they're worded. An unqualified (clean) opinion keeps the standard structure with no extra explanation needed. A qualified, adverse, or disclaimer opinion each adds a "Basis for Qualified/Adverse Opinion" paragraph before the opinion itself, explaining exactly what went wrong.
Here's how the four compare, drawn from the structure documented by Datasnipper's audit reporting guide and CLFI's audit report definitions:
| Opinion type | What it means | Extra content added | Red flag for readers |
|---|---|---|---|
| Unqualified (clean) | Financials are fairly presented, no material issues found | None; standard structure only | None, this is the result lenders want to see |
| Qualified | Financials are fairly presented except for one specific, isolated issue | A "Basis for Qualified Opinion" paragraph naming the exact issue | One named problem, contained and explained |
| Adverse | Financials do not fairly present the company's position; misstatements are pervasive | A "Basis for Adverse Opinion" paragraph with full detail | Serious; lenders and investors should treat this as a stop sign |
| Disclaimer | The auditor could not gather enough evidence to form any opinion at all | A "Basis for Disclaimer of Opinion" paragraph explaining what was missing | Worse than adverse in some eyes, since it means the auditor couldn't even assess the damage |
Rank these from best to worst for a reader evaluating a company: unqualified, qualified, adverse, disclaimer. An adverse opinion and a disclaimer both signal real trouble, but a disclaimer is arguably more alarming because it means the auditor was blocked from doing the work at all, not just that they found something wrong.
What Is the Difference Between Key Audit Matters and Critical Audit Matters?
Key Audit Matters (KAM) under ISA 701 and Critical Audit Matters (CAM) under PCAOB AS 3101 serve the same basic function, flagging the areas of an audit that needed the most judgment, but they come from different rulebooks and apply in different countries. KAM governs reports for listed entities under international standards; CAM governs reports for US public companies audited under PCAOB rules.
| Feature | Key Audit Matters (KAM) | Critical Audit Matters (CAM) |
|---|---|---|
| Governing standard | ISA 701 | PCAOB AS 3101 |
| Applies to | Listed entities under international standards | US public companies |
| Selection basis | Matters of most significance in the audit, per auditor judgment | Matters communicated to the audit committee, relating to material accounts, involving especially challenging judgment |
| Required content | Why the matter was significant, how the audit addressed it | Same structure: description, auditor's response, why it was challenging |
| Why it matters | Gives investors visibility into audit judgment calls, not just the final opinion | Same investor-transparency goal, under a different regulatory regime |
If you're writing for a US-based SaaS company that touches public company compliance, use CAM and cite PCAOB AS 3101. If you're writing for an international or UK audience, use KAM and cite ISA 701. Mixing the two terms in one piece without naming the standard behind each is a common and avoidable error.
How Does Audit Report Content Change for Small or Private Companies?
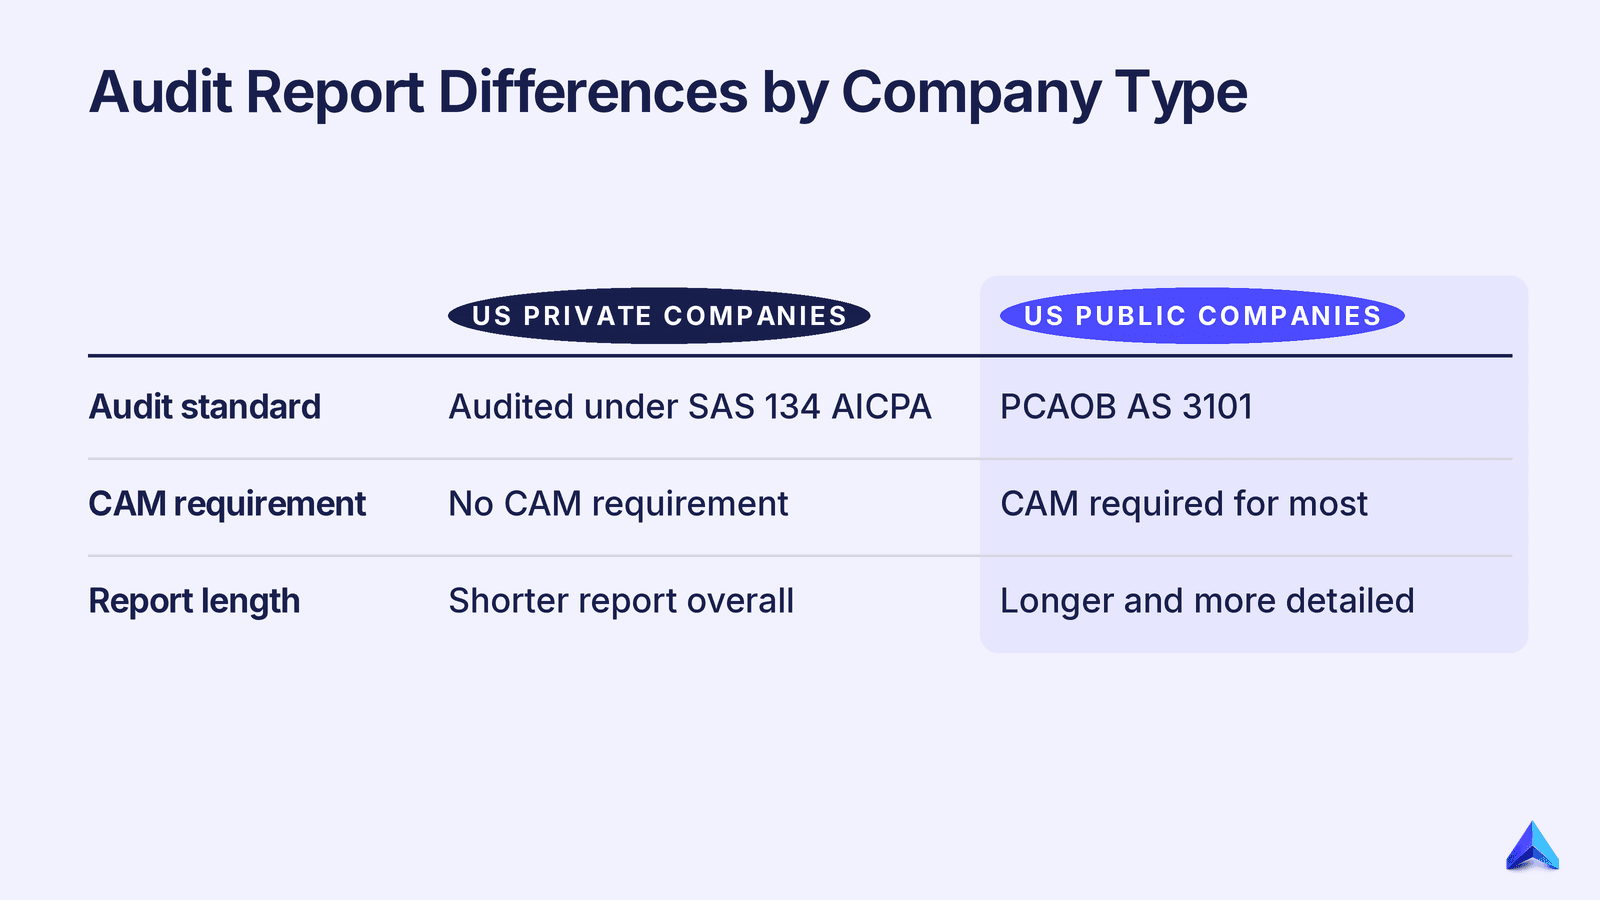
Private and small companies typically receive shorter, simpler audit reports because they're audited under SAS 134 (US, AICPA) rather than PCAOB standards, and they rarely trigger a Key Audit Matters section since that requirement is mostly aimed at listed entities. The AICPA reports that approximately 60% of audit engagements in the US involve private companies audited under SAS 134 (AICPA, 2024). A small business audit report still needs every one of the eight core sections, just without the extra layers public companies face.
Jurisdiction adds another layer on top of company size. Here's a quick map of what differs:
-
US private companies: audited under SAS 134 (AICPA), no CAM requirement, shorter report overall.
-
US public companies: audited under PCAOB AS 3101, CAM required for most, longer and more detailed.
-
International entities (most non-US markets): audited under ISA 700/701, KAM required for listed entities only.
-
UK companies: must also meet Companies Act reporting requirements layered on top of ISA, adding specific statutory disclosures.
-
Indian companies: subject to CARO (Companies Auditor's Report Order) reporting in addition to standard audit content, covering extra points like fixed asset verification and loan compliance.
For a content or marketing team producing a how-to-do-a-content-audit style piece for an accounting client, name the right standard for the client's market. Readers (and AI summarizers) trust specificity, and generic "an audit report must include X" claims that ignore jurisdiction read as thin.
What Does a Full Audit Report Template Look Like?
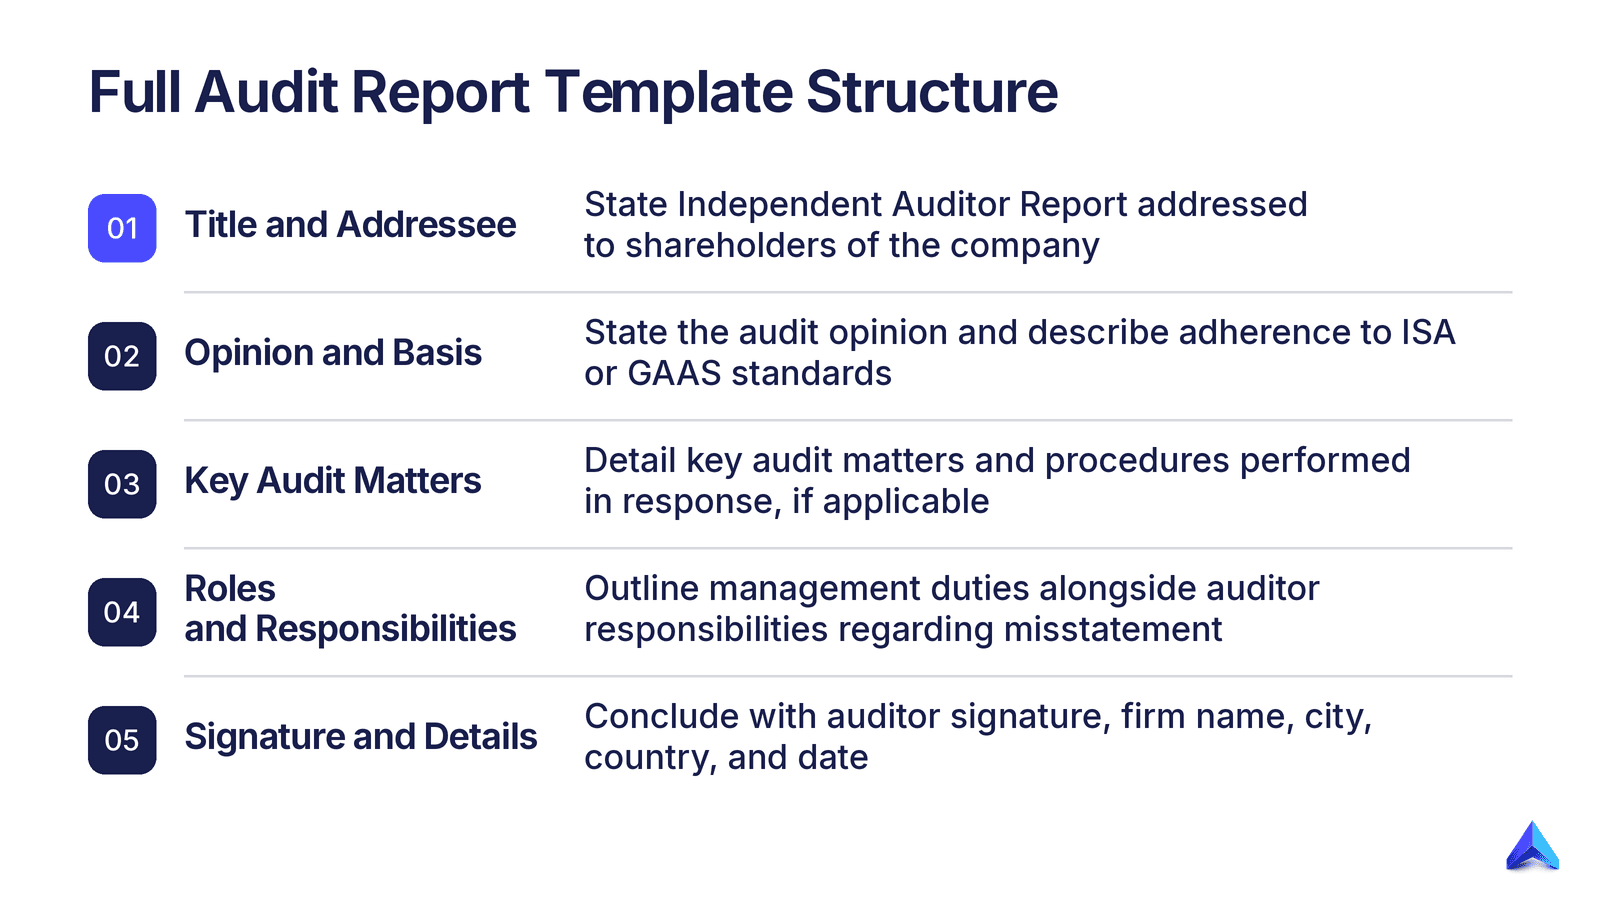
A full audit report template runs through the eight required sections in a fixed order, with bracketed placeholders for the specifics. This is the structure an auditor fills in, and it closely matches what the IIA's Audit Report Writing Toolkit recommends for clarity and consistency.
-
Title: "Independent Auditor's Report"
-
Addressee: "To the Shareholders of [Company Name]"
-
Opinion paragraph: "We have audited the financial statements of [Company Name], which comprise the balance sheet as at [date], and the statement of income, changes in equity, and cash flows for the year then ended... In our opinion, the accompanying financial statements present fairly, in all material respects, [the financial position of the Company]..."
-
Basis for opinion: "We conducted our audit in accordance with [ISA / GAAS]. Our responsibilities under those standards are further described in the Auditor's Responsibilities section... We believe the audit evidence we have obtained is sufficient and appropriate to provide a basis for our opinion."
-
Key Audit Matters (if applicable): "[Matter] was considered a key audit matter because [reason]. Our response to this matter included [procedures performed]."
-
Responsibilities of management: "Management is responsible for the preparation and fair presentation of these financial statements... and for such internal control as management determines is necessary..."
-
Auditor's responsibilities: "Our objectives are to obtain reasonable assurance about whether the financial statements as a whole are free from material misstatement, whether due to fraud or error..."
-
Signature, date, and place: "[Auditor's Signature] [Firm Name] [City, Country] [Date]"
A real-world version of this structure is visible in the NAIHC sample independent auditor's report, which walks through each paragraph nearly word for word against the template above. Comparing a template against a live sample like this is the fastest way to check you have not missed a required section.
If your own audit process still needs a first pass before a formal report, our guide to running a content audit and our SEO audit walkthrough cover the same question from the content and marketing side, where "audit" means something related but distinct from the financial sense used here.
A Short Glossary for Anyone Writing About Audit Reports
-
Material misstatement: An error or omission large enough to change a reasonable reader's decision about the company.
-
Pervasive: Used to describe a problem so widespread it affects the financial statements as a whole, not one isolated line item.
-
Sufficient appropriate evidence: The standard an auditor must meet before forming any opinion; too little evidence leads to a disclaimer.
-
True and fair view: The core test auditors apply when deciding whether financials fairly represent a company's position.
-
GAAS: Generally Accepted Auditing Standards, the US rulebook for how audits are conducted.
-
GAAP: Generally Accepted Accounting Principles, the US rulebook for how financials are prepared (different from GAAS).
-
ICFR: Internal Control over Financial Reporting, the systems a company uses to prevent and catch errors before an audit even starts.
Mixing up GAAS and GAAP is one of the most common errors in content written by non-accountants. One governs the audit; the other governs the books being audited.
常見問題
What are the content of audit report?
The content of audit report includes a title, addressee, opinion paragraph, basis for opinion, management and auditor responsibility statements, and a signature with date and place. Conditional sections like Key Audit Matters, Emphasis of Matter, or Going Concern appear only when specific facts in the audit trigger them.
What is the content of a personnel audit report?
A personnel audit report, distinct from a financial audit report, typically covers hiring compliance, policy adherence, training records, and HR process gaps, with findings and recommendations instead of a formal opinion paragraph. It follows a findings-and-recommendations format rather than the ISA/PCAOB opinion structure used in financial audits.
Who signs an audit report?
The engagement partner or the audit firm itself signs the report, along with the city and date of signing. For public companies under PCAOB rules, the firm's name is required; individual partner signatures are more common under some international jurisdictions.
How long is an audit report?
A standard unqualified audit report runs two to four pages. Research by Deloitte found that the average audit report length increased by 23% between 2015 and 2023, driven primarily by expanded Key Audit Matters and Going Concern disclosures (Deloitte, 2023). Reports with Key Audit Matters, Going Concern paragraphs, or a qualified or adverse opinion routinely run longer, since each conditional section adds its own explanatory paragraph.
What happens if an audit report is qualified?
A qualified opinion means the financials are fairly presented except for one specific, named issue, and lenders or investors typically treat it as a flag to investigate further rather than an automatic rejection. The report will include a "Basis for Qualified Opinion" paragraph explaining exactly what the issue is. If your team handles SEO or content work for accounting, legal, or financial services clients, getting this terminology precise is part of building topical authority that both Google and AI answer engines recognize. For a broader look at structuring audit-adjacent content that ranks, see our SEO for accountants guide or get in touch through Project Rankup's contact page if you want help building out a content plan around this kind of technical subject.